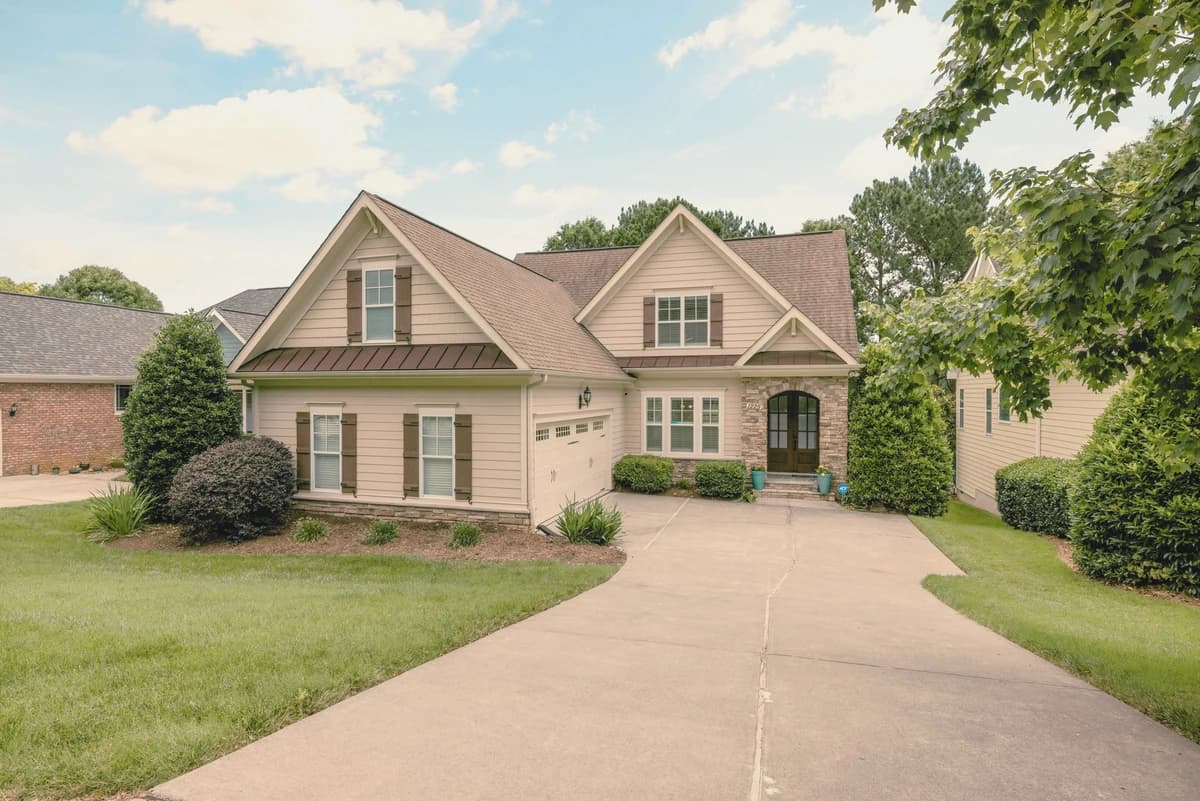
His PaymentStarted at $16,645.It Became $48,220.
Correct paperwork with a jump no borrower could ever see coming.
- Sale Closed:
- August 2007
- Loan Amount:
- $5,175,000
- Loan Type:
- Payment-option adjustable-rate mortgage
The monthly payment
- At the Start:
- $16,645
- Before the Reset:
- $19,235
- After the Reset:
- $48,220
$28,985 more per month
Roughly 2.5 times the payment immediately before it.
Here’s what the files revealed:
The Payment Didn’t Cover the Interest
The minimum payment was based on a 1% rate, while interest accrued at about 8.85%.
Unpaid Interest Was Added to the Loan
Paying the minimum left a shortfall each month. That shortfall increased the amount owed.
The Growing Balance Hit Its Limit
The loan could grow to 115% of its original amount: $5,951,250. At that limit, the payment reset to repay the balance over the remaining term.
How the mismatch was found:
The examiner rebuilt the loan month by month, tracking unpaid interest, the growing balance and the payment required when the cap was reached.
What the Homera Check would have caught:
Although the disclosures were within legal tolerances, the Homera Check would have flagged the risk involved before signing.
What the Homera Audit would have done:
The Homera Audit would have shown how unpaid interest increased the loan balance and triggered the jump to $48,220 a month. It would also have checked whether the interest, balance and payment reset were calculated according to the loan agreement. In this case, the review found accurate disclosures, the danger was the loan’s structure.
Uncovered using the forensic methodology Homera is built on.
Could your mortgage payment make this jump?
This homeowner didn't know what to look for. Most people wouldn't. The Homera Check was designed to prevent this from happening.
Homera independently checks the numbers, terms and activity behind your mortgage — before you sign and for as long as you own your home.