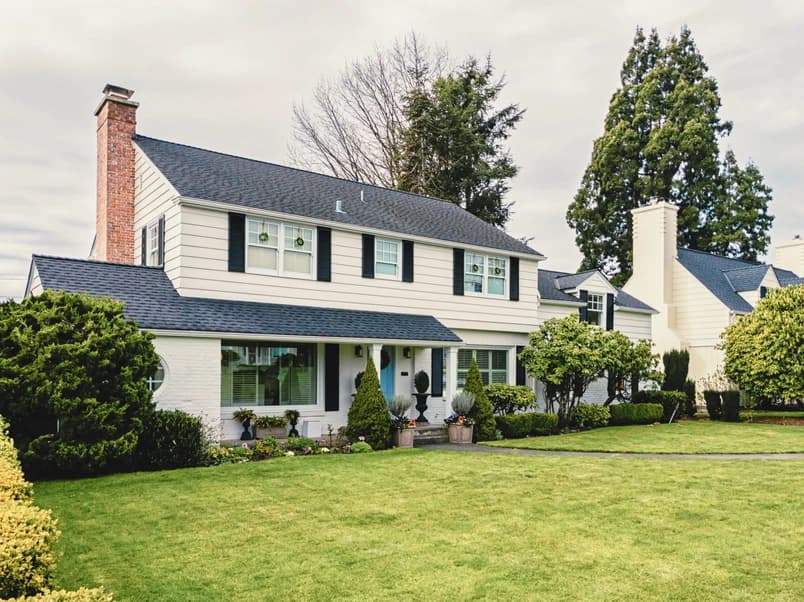
She Was Current.Then Her MortgageCompany StoppedTaking Her Payments.
Escrow errors, stopped autopay and the modification added more debt.
- Sale Closed:
- July 2005
- Loan Amount:
- $235,000
How it happened
- 2012
Insurance paid twice
The servicer paid two insurers on the same day: $3,934 total. The resulting escrow shortfall was passed to the homeowner.
- Monthly Escrow:
- $313.41 ➔ $616.99
- Total Monthly Payment:
- $1,822.03 ➔ $2,125.61
- 2013
Autopay stopped
The servicer stopped automatic withdrawals while the account was current. No reason was recorded. Delinquency began at that point.
- 2014
A tax charge that didn’t match
The escrow withdrawal far exceeded the city's assessments for the same period.
- Recorded as Property Taxes:
- $313.41 ➔ $616.99
- City Records for Maximum Owed:
- About $1,394.26
- 2017
The modification added debt
- Added to interest-bearing principal without itemization.
- $131,309.39
- Scheduled payments over the modified term.
- $418,281.40
- Balloon still due at maturity.
- $234,362.08
After those scheduled payments, she would still owe roughly the original loan amount.
- 2022
Autopay stopped again
A different servicer stopped withdrawals while the account was current. A default notice followed 38 days later.
How the mismatch was found:
The examiner rebuilt the account payment by payment and checked escrow disbursements against the city's published tax assessments.
What the Homera Monitor would have caught:
The Homera Monitor would have flagged recorded changes, such as a mortgage assignment or foreclosure filing, prompting further review.
What the Homera Audit would have caught:
The Homera Audit would have uncovered the duplicate insurance payments, the inflated property-tax charge, and when stopped withdrawals led to delinquency. It also would have identified the $131,309.39 in unexplained charges added to the loan and the $234,362.08 balloon payment left due at maturity.
Uncovered using the forensic methodology Homera is built on.
If your autopay stopped, how quickly would you know?
This homeowner didn't know what to look for. Most people wouldn't. The Homera Monitor and Homera Audit were designed to prevent this from happening.
Homera independently checks the numbers, terms and activity behind your mortgage — before you sign and for as long as you own your home.